Investor Hub
Protect Everything You've Built From a Single Bad Day
A lawsuit, a fire, a flood, a tenant injury — any one of them can erase years of compounded returns if you're not set up right. The protection you have when something happens is whatever you put in place before it did.
Disclaimer
We do not provide legal, tax, or insurance advice. The information below is educational. Entity structure, asset protection, and insurance decisions carry legal, tax, and coverage consequences specific to your situation — consult a qualified attorney, CPA, and licensed insurance broker before making any of them.
The team
The Team You Should Be Using
For this topic, you'll want:
- Insurance Broker (commercial-capable) — coverage and gap analysis
- Real Estate Attorney — entity structure and liability
- Estate Planning Attorney — trusts, succession, asset protection structuring
- CPA (with real estate specialization) — how entity choice affects tax
- Real Estate Advisor (us) — to raise the protection conversation early and get the right specialists to the table
Nobody buys a property thinking about the lawsuit, the fire, or the tenant who slips on the stairs. That's exactly why so many investors are exposed. Insurance and asset protection are the unglamorous layer that does nothing for your returns — right up until the day it's the only thing standing between one bad event and years of compounded Equity In real estate investing, equity is the difference between a property's current market value and the balance owed on it. Equity grows through loan paydown and appreciation, and it's the denominator in return on equity (ROE). . The hard truth: whatever protection you have when something goes wrong is whatever you set up before it did. There's no retroactive fix. This page is about getting it right early.
What insurance and asset protection are
In real estate investing, insurance transfers the financial risk of specific events — fire, storm, liability claims, loss of rent — to an insurer in exchange for a premium. Asset protection is the broader practice of structuring how you own property — through entities like LLC (Limited Liability Company) A limited liability company (LLC) is a business structure allowed by state statute that can separate ownership of assets and, when properly formed and maintained, limit how far a liability can spread. How an LLC is taxed is a separate question from how it protects, and both depend on details. Tax classification is governed by the IRS; formation and protection by state law. Educational only — consult an attorney and CPA. , plus tools like umbrella policies and, in some cases, trusts — so that a problem with one property or one claim can't reach your other assets. Insurance handles the loss when something happens. Asset protection limits how far the damage can spread. Serious investors use both, in layers.
Why it matters more as you grow
One rental with a homeowner-style policy is a manageable risk. A portfolio is a different exposure entirely — more properties, more tenants, more ways for something to go wrong, and far more Equity In real estate investing, equity is the difference between a property's current market value and the balance owed on it. Equity grows through loan paydown and appreciation, and it's the denominator in return on equity (ROE). at stake if it does. The investor with ten properties held the wrong way and the wrong coverage isn't ten times as exposed; they're exposed to a single event cascading across everything they own. The whole point of getting structure and coverage right is to make sure a problem stays contained to the property it started on.
The layers, in plain terms
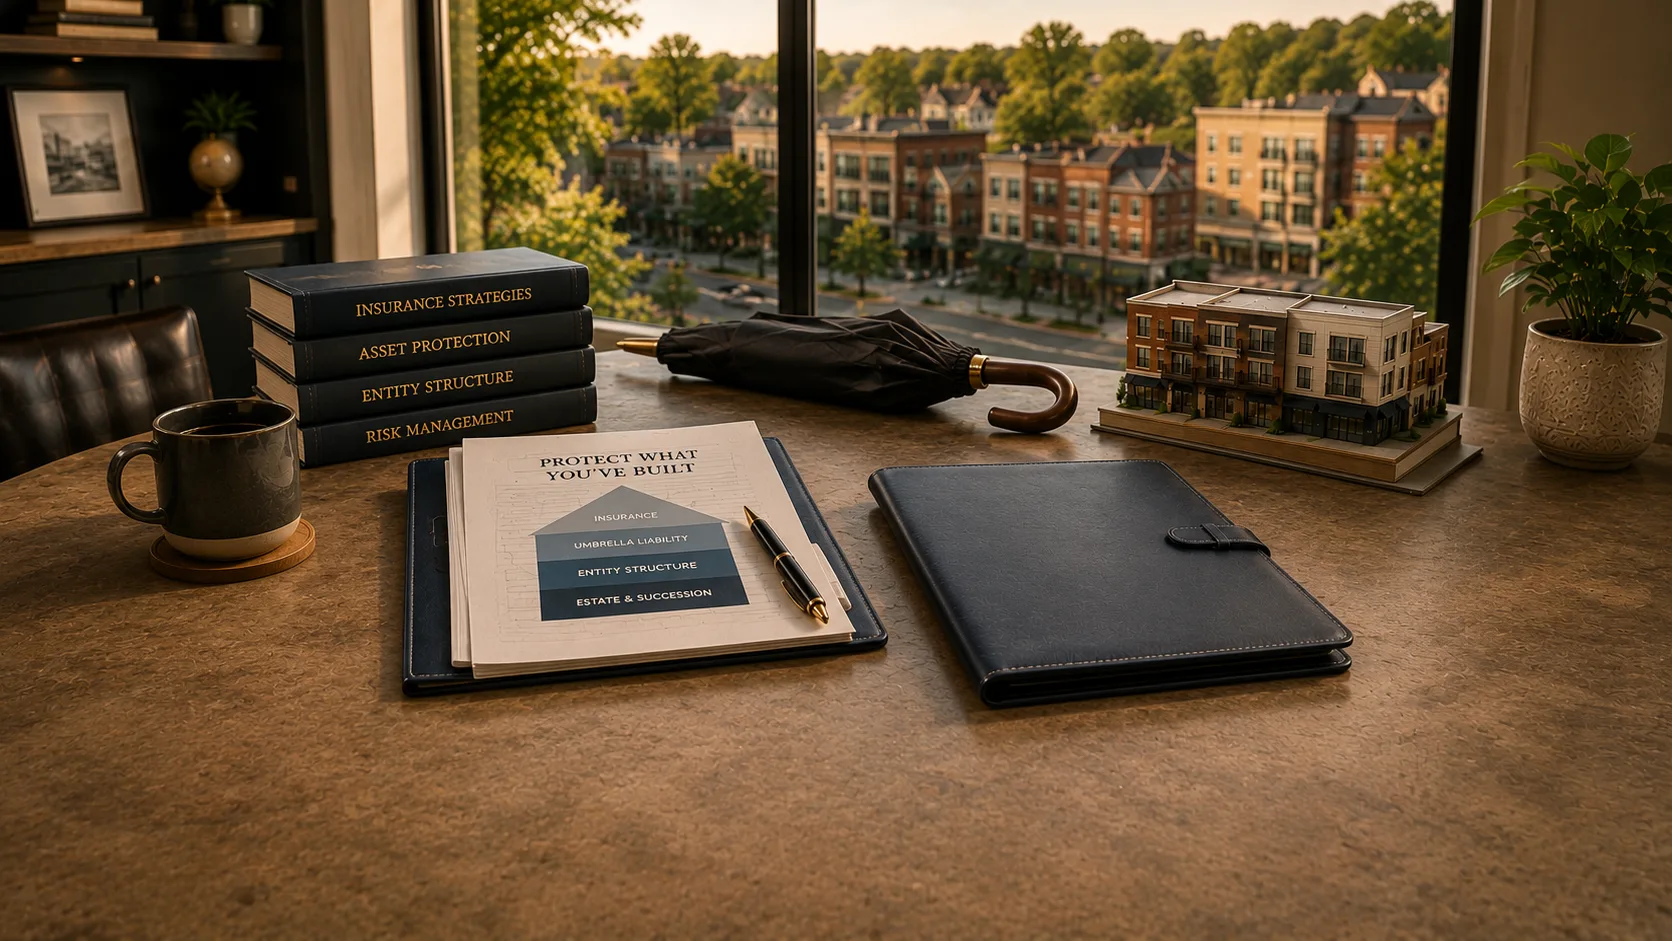
Most protection plans are built in layers.
- Property and liability insurance on each property handles direct loss and claims.
- An umbrella policy sits on top, adding liability coverage beyond the limits of the underlying policies.
- Entity structure — commonly LLC (Limited Liability Company) A limited liability company (LLC) is a business structure allowed by state statute that can separate ownership of assets and, when properly formed and maintained, limit how far a liability can spread. How an LLC is taxed is a separate question from how it protects, and both depend on details. Tax classification is governed by the IRS; formation and protection by state law. Educational only — consult an attorney and CPA. — separates ownership so a claim against one property doesn't automatically reach the others or your personal assets.
- Estate and succession planning — trusts and related tools — handles what happens to the portfolio over the long term.
How these layers fit together depends entirely on your situation, which is why this is a conversation for professionals, not a template.
On LLCs — what they do and don't do
The LLC (Limited Liability Company) A limited liability company (LLC) is a business structure allowed by state statute that can separate ownership of assets and, when properly formed and maintained, limit how far a liability can spread. How an LLC is taxed is a separate question from how it protects, and both depend on details. Tax classification is governed by the IRS; formation and protection by state law. Educational only — consult an attorney and CPA. is the most talked-about asset protection tool, and also the most misunderstood. Investors often assume forming an LLC is a magic shield. It's a real and useful tool — but it has to be set up and maintained correctly to do its job, and the protection it provides has limits and conditions defined by state law. How an LLC is taxed is a separate question from how it protects you, and both depend on details a CPA and attorney need to handle together.
"A Limited Liability Company (LLC) is a business structure allowed by state statute. ... Depending on elections made by the LLC and the number of members, the IRS will treat an LLC either as a corporation, partnership, or as part of the owner's tax return (a disregarded entity)."
In other words, "form an LLC" isn't a single decision — it's several. How it's structured affects your taxes, how it's maintained affects whether the liability protection actually holds, and the rules that govern it are set by the state where it's formed (in Pennsylvania, the Uniform Limited Liability Company Act). This is precisely why the attorney, the CPA, and the insurance broker belong at the same table.
Common mistakes
- Carrying a personal homeowner-style policy on a rental property instead of a proper landlord/dwelling policy.
- Skipping the umbrella policy that would have covered the claim that exceeded the base limits.
- Forming an LLC (Limited Liability Company) A limited liability company (LLC) is a business structure allowed by state statute that can separate ownership of assets and, when properly formed and maintained, limit how far a liability can spread. How an LLC is taxed is a separate question from how it protects, and both depend on details. Tax classification is governed by the IRS; formation and protection by state law. Educational only — consult an attorney and CPA. and then ignoring the formalities that keep its protection intact.
- Holding everything in one entity, so a single claim reaches the whole portfolio.
- Assuming flood is covered when it almost never is under a standard policy.
- And the most common one: never reviewing any of it again after the day of purchase, while the portfolio and the exposure both keep growing.
How we use this with investors
We're not your attorney, your CPA, or your insurance broker — and we'll never pretend to be. What we do is make sure the conversation happens before you need it, and that the right specialists are at the table while there's still time to structure things properly. Most investors don't think about protection until something forces them to, and by then the options have narrowed. Our role is to raise it early and coordinate the professionals who put it in place.
Grounding
Standards and outside rules
The rules here come from outside our lane, and they matter. How an LLC is taxed is governed by the IRS — see IRS, Limited Liability Company (LLC) . How an LLC is formed and what protection it provides is governed by state law (in Pennsylvania, the Uniform Limited Liability Company Act, Title 15). Insurance licensing and coverage requirements are governed by state insurance regulators (the Pennsylvania Insurance Department) and shaped by national models from the National Association of Insurance Commissioners. Flood coverage runs through FEMA's National Flood Insurance Program . Everything else here is general education — not legal, tax, or insurance advice.
Vocabulary
Related real estate investment terms: asset protection, landlord insurance, dwelling policy, commercial general liability, umbrella policy, LLC, limited liability company, disregarded entity, charging order protection, trust, estate planning, flood insurance, NFIP, liability exposure.
We do not provide legal, tax, or insurance advice. The information above is educational and does not address your specific circumstances. Entity structure and insurance decisions carry real legal, tax, and coverage consequences — consult a qualified attorney, CPA, and licensed insurance broker before acting.
Is your portfolio actually protected — or just insured?
Coverage and structure are easy to get wrong and expensive to discover late. If you're not sure your entities and policies would actually hold up when something goes wrong, that's exactly the conversation to have before something does. We'll help you get the right professionals to the table.